This article is general information, not financial advice. Read our disclaimer and speak to a registered professional about your own circumstances.
Private wealth management is a holistic service for wealthy individuals and families that combines investing with tax, estate, retirement, and cash-flow planning. Asset management is narrower: a professional manages a portfolio or fund to grow it within a set strategy. Asset management is often one part of wealth management.
Your RSUs vest, your savings pass a number you never expected to see, and within a month two offers land in your inbox. Your bank invites you to a “private wealth management” consultation, and an investment app suggests a “professionally managed portfolio.” Both promise to look after your money, but they don’t do the same job.
The short version of private wealth management vs asset management: asset management is the investing piece, where a professional runs a portfolio or fund toward a set goal. Private wealth management puts that investing inside a full plan for your taxes, retirement, estate, and cash flow. This guide explains how the two differ in scope, clients, fees, and legal duty, and gives you a simple test for which one fits your situation.
Private Wealth Management vs Asset Management: What Is the Difference?
The main difference is scope: asset management looks after your investments, while private wealth management looks after your whole financial life, including those investments.
| Feature | Private wealth management | Asset management |
|---|---|---|
| What it manages | Your full financial picture: investments, taxes, retirement, estate, cash flow | A portfolio or fund |
| Main goal | Grow, protect, and pass on wealth in line with a written plan | Meet a stated return goal or benchmark within a set strategy |
| Typical clients | Affluent and high-net-worth individuals and families | Institutions such as pensions and endowments, plus individuals through funds and managed accounts |
| Services | Investing plus tax-aware planning, retirement income, estate coordination, insurance review, giving | Research, security selection, asset allocation, rebalancing, reporting |
| How it is paid | Often a percentage of assets managed; some firms charge flat or hourly fees | A percentage of assets managed or a fund’s expense ratio; some funds add performance fees |
| Legal duty | Depends on registration: investment advisers owe a best-interest duty at all times | Depends on registration: same rules as for any adviser or broker |
| How often you talk | Regular meetings, often with one main contact | Little or no personal contact; you get statements and reports |
Commenters in r/FinancialCareers explain it simply: asset managers look after the money, while wealth managers look after the people who own it.
What Is Private Wealth Management?
Private wealth management is a personalised service that manages a wealthy client’s investments and coordinates their wider financial plan in one relationship.
The “private” part means a high-touch, one-to-one service rather than a product off the shelf. Firms often set a minimum amount of investable assets before they’ll take you on, and that minimum varies widely by firm, so ask before your first meeting. In return, you usually get a named adviser or small team who knows your family, your business, and your goals.
What does a private wealth manager do?
A private wealth manager builds a plan for your money and then makes sure every part of it works together. Typical services include:
- Investment management: Setting your asset allocation and either running the portfolio or choosing outside managers and funds.
- Tax-aware planning: Deciding which accounts to draw from first and timing sales to manage capital gains, in coordination with your CPA.
- Retirement income: Planning how much you can spend and from which accounts, including choices like Roth IRA vs 401k contributions.
- Estate coordination: Working with your attorney on wills, trusts, and beneficiaries, and flagging state estate tax exposure where you live.
- Insurance and giving: Reviewing life and disability coverage and setting up charitable gifts.
- Cash flow: Budgeting for big goals like a home, school fees, or a business purchase.
Who is private wealth management for?
It suits people whose finances have several moving parts that affect each other. Common examples:
- Business owners planning a sale or succession.
- Employees with large stock options or RSUs.
- Families who’ve received an inheritance.
- People with property or accounts in more than one state or country.
If you live in the US and keep accounts abroad, the plan also has to respect US reporting rules. That can mean FBAR and FATCA reporting for foreign accounts, and PFIC rules for foreign funds if you own non-US mutual funds or ETFs. A wealth manager with cross-border experience should coordinate these with your tax preparer.
What Is Asset Management?
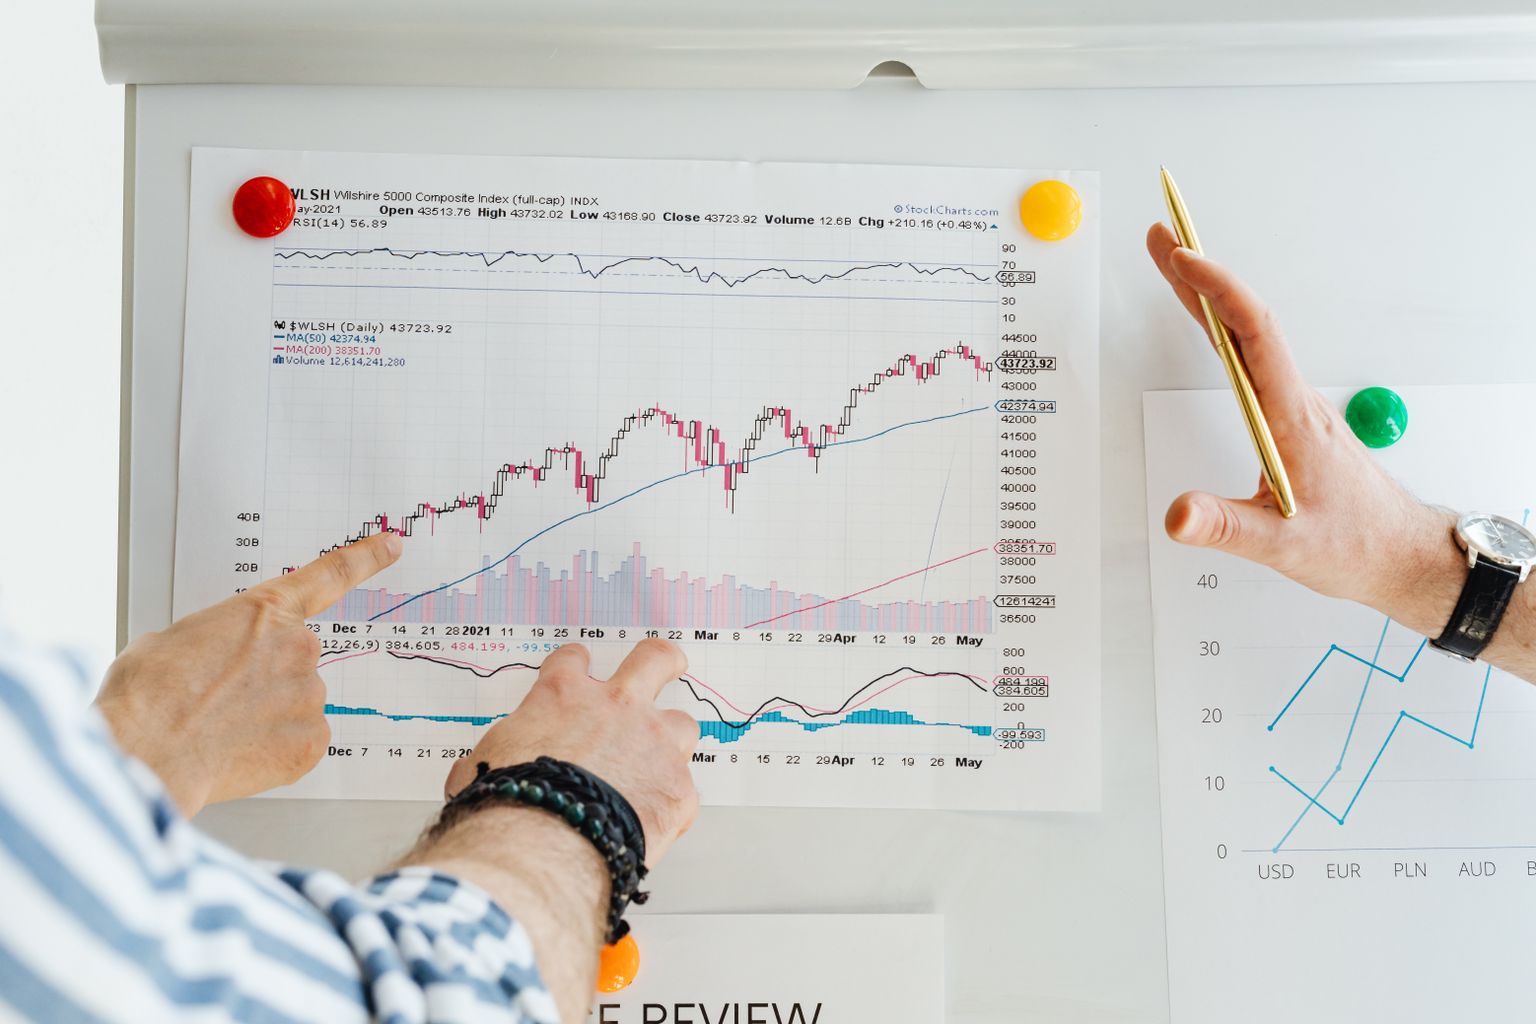
Asset management is the professional management of a portfolio or fund to reach a stated goal, such as beating a benchmark or producing steady income.
Asset management applies the same ideas behind how investing works at scale, with a professional making the buy and sell decisions for you.
What does an asset manager do?
An asset manager makes the investment decisions inside a defined strategy, often called a mandate. The work covers:
- Research: Studying companies, bonds, markets, and economic data.
- Security selection: Picking the stocks, bonds, or other assets that fit the mandate.
- Asset allocation: Setting the mix across asset classes, from equities and bonds to alternatives. Debates like crypto vs stocks are an allocation question at this level.
- Rebalancing: Bringing the portfolio back to its targets as markets move.
- Reporting: Sending clients or fund shareholders regular performance updates.
An asset manager usually doesn’t handle your taxes, estate plan, or budget. Their job ends at the portfolio.
Institutional vs individual asset management
Asset managers serve two broad groups. Institutional clients, such as pension funds, endowments and insurers, hand over large sums under detailed mandates. Individuals reach the same professional management through mutual funds, ETFs and managed accounts.
If you own a mutual fund, you already use an asset manager. The SEC’s investor.gov page on mutual funds explains that a fund’s portfolio “is managed by an SEC-registered investment adviser.”
How Do Fees Compare in Private Wealth Management vs Asset Management?
Private wealth management usually costs more in total because it bundles more services, but the fee structure is what you should compare.
The common fee models are:
- Percentage of assets under management: The SEC’s investor.gov notes that an investment adviser’s fee “is typically based on the value of all of the assets held in your account.”
- Flat or retainer fee: A fixed yearly amount for planning and advice.
- Hourly fee: You pay for the time you use, which suits one-off planning questions.
- Fund expense ratio: The annual cost of running a mutual fund or ETF, taken from the fund’s assets.
- Performance fee: A share of gains, mostly charged by hedge funds and some private funds.
These layers can stack. If a wealth manager charges an advisory fee and invests you in funds with their own expense ratios, you pay both.
Small differences grow over time. The SEC’s Understanding Fees page shows a hypothetical $100,000 investment growing 4% a year for 20 years:
| Annual fee | Approximate value after 20 years |
|---|---|
| 0.25% | $208,000 |
| 0.50% | $198,000 |
| 1.00% | $179,000 |
Ask any provider for their total yearly cost in dollars, including fund costs, and compare that figure rather than the headline rate.
Are Wealth Managers and Asset Managers Fiduciaries?
It depends on how the person or firm is registered, not on whether they call themselves a wealth manager or an asset manager.
The SEC’s investor.gov site sets out two main standards:
- Investment advisers: According to investor.gov’s guide to investment advisers, “Investment advisers are required to act in your best interest and not put their interest ahead of yours.” This duty covers the whole advisory relationship.
- Brokers (broker-dealers): Investor.gov’s guide to brokers explains that brokers must act in your best interest “when making a recommendation,” under the SEC’s Regulation Best Interest. They’re usually paid per transaction.
Some professionals are registered as both, and may act under different standards for different accounts. Titles like “wealth manager,” “financial advisor,” or “private banker” aren’t licenses, and investor.gov warns that initials after a name don’t necessarily mean better service.
The fastest way to know which standard applies to you is to ask for the firm’s Form CRS. Registered advisers and brokers must give this short relationship summary to retail investors, and investor.gov/CRS explains that it covers services, fees, conflicts of interest, the standard of conduct, and any disciplinary history.
Is Asset Management Part of Wealth Management?
Yes, usually. Asset management is one layer inside wealth management, rather than the other way around.
A wealth manager typically works in three layers:
- The plan: Your goals, taxes, retirement timeline, and estate wishes.
- The allocation: The mix of stocks, bonds, cash, and other assets that fits the plan.
- The managers and funds: The people or products that run each slice, either the firm’s own portfolio team or outside asset managers, mutual funds and ETFs.
So when you hire a wealth manager, you’re often hiring an asset manager too, either directly or through the funds they choose.
How Is Wealth Management Different From Private Banking or a Financial Advisor?
Private banking focuses on banking and lending, “financial advisor” is a broad title, and wealth management combines planning with investing.
| Service | Main focus | What to check |
|---|---|---|
| Private banking | Premium banking: deposits, lending, credit lines, cash management | Whether investment advice comes from a separately registered team |
| Financial advisor | A broad title that can cover planners, brokers and advisers | How they’re registered and how they’re paid |
| Wealth management | A holistic plan plus investment management | What the fee covers and who manages the investments |
Many banks offer private banking and wealth management under one roof, so ask which part of the business provides each service and which rules apply.
Which Do You Need: Private Wealth Management or Asset Management?
You likely need private wealth management if your finances involve several connected decisions, and asset management alone if you mainly want your investments handled.
Answer yes or no to each question:
- Do you have tax questions beyond a standard return, such as stock compensation, a business, or rental income?
- Do you need an estate plan, a trust, or help passing assets to children?
- Do you own a business or expect a large one-time payout?
- Do you have accounts or property in more than one country or state?
- Would you rather hand over planning decisions than spend your own time on them?
- Are your investable assets large enough to meet the minimums firms in your area ask for?
Mostly yes points toward private wealth management. Mostly no suggests that asset management, through low-cost funds or a managed account, may cover what you need.
Hypothetical example 1: Priya is a 34-year-old engineer with $80,000 in a 401(k) and a taxable brokerage account. Her taxes are simple, she has no dependents, and she’s happy to review her accounts twice a year. Diversified funds or a managed account give her professional asset management without paying for planning she doesn’t use.
Hypothetical example 2: Mark is 58, about to sell his company for roughly $6 million, owns property in two states, and wants to set up trusts for his grandchildren. His decisions on the sale, taxes, estate, and retirement income all affect each other, which is exactly what a private wealth manager coordinates.
How Can You Check a Wealth Manager or Asset Manager Before Hiring One?
Check their registration, read their disclosures, and ask how they’re paid before you sign anything.
- Search the SEC’s IAPD: The Investment Adviser Public Disclosure database shows whether a person or firm is a registered adviser.
- Search FINRA BrokerCheck: BrokerCheck shows brokers’ registrations, employment history, and complaints.
- Read Form CRS: It lists the firm’s services, fees, conflicts, and standard of conduct on a few pages.
- Read Form ADV Part 2: An adviser’s brochure explains fees, services, and conflicts in more detail.
- Ask two direct questions: “How are you paid, in dollars, on my account?” and “Do you act as a fiduciary at all times for every account I hold with you?”
Look for any disciplinary history in both tools, and check the person as well as the firm.
Asset Management vs Wealth Management Careers: What Is the Difference?
Asset management careers centre on research and portfolio decisions, while wealth management careers centre on advising clients.
Asset management roles include research analyst, portfolio manager, and trader. Wealth management roles include financial planner, client adviser, and relationship manager. According to the US Bureau of Labor Statistics, the 2025 median pay was:
- Personal financial advisors: $105,070 a year, with employment projected to grow 1% from 2025 to 2035 (BLS).
- Financial analysts, the BLS group that includes portfolio managers: $103,570 a year, with 7% projected growth (BLS).
Actual pay depends heavily on firm, location, seniority, and bonuses.
Conclusion
Private wealth management vs asset management is a question of how much of your financial life you want someone to coordinate. If you mainly need your investments run well, asset management through funds or a managed account may be enough. If taxes, a business, an estate, or cross-border assets are tangled together, a private wealth manager brings it all into one plan. Either way, check registration, read Form CRS, and compare total costs in dollars. Reading a few investing guides on DA Finance Blog first makes those conversations easier, and a qualified, registered professional can then apply the ideas to your own situation.
Frequently Asked Questions
Q1: What’s the difference between investment management and wealth management?
A: Investment management is another name for asset management: a professional manages your portfolio. Wealth management includes investment management and adds planning for taxes, retirement, estate, and cash flow, so every financial decision fits one plan.
Q2: What does private wealth management mean?
A: Private wealth management means personalised, holistic financial management for high-net-worth clients. “Private” refers to the one-to-one, high-touch service, usually from a dedicated adviser or team, and firms often set a minimum amount of assets before taking on a client.
Q3: Is wealth management a part of asset management?
A: Usually it’s the reverse: asset management is one part of wealth management. A wealth manager builds your overall plan, then either manages the investments in-house or uses outside asset managers and funds to run them.
Q4: Are portfolio management and wealth management the same?
A: No. Portfolio management is the investment piece: choosing, monitoring, and rebalancing your holdings. Wealth management covers the whole financial picture, including taxes, retirement income, estate planning, and insurance, with portfolio management as one part of it.
Q5: Is wealth management more expensive than asset management?
A: Often, because it covers more services. Compare the total yearly cost in dollars, including the advisory fee and any fund expense ratios, rather than the headline rate. The SEC shows that even small fee differences add up over 20 years.
Q6: What is the 72 rule in wealth management?
A: The Rule of 72 estimates how long an investment takes to double: divide 72 by the annual rate of return. Investor.gov’s example is 9%, which doubles money in about 8 years. It’s a quick estimate, not a promise of returns.
Q7: What pays more, asset management or wealth management?
A: It depends on the role, firm, and seniority. BLS figures for 2025 show similar median pay: $105,070 for personal financial advisors and $103,570 for financial analysts, the group that includes portfolio managers. Bonuses can widen the difference at senior levels.