Published: October 16, 2026
Disclaimer: General information only, not tax or investment advice. PFIC rules are complex and change; talk to a US tax professional about your situation.
A PFIC, short for passive foreign investment company, is a non-US corporation that earns mostly passive income or holds mostly passive assets, and the label covers far more than shady offshore shells. That foreign mutual fund you bought through a bank in Mumbai, the Irish-domiciled ETF in your European brokerage account, a Canadian index fund: all of these are usually PFICs in the eyes of the IRS. If you are a US citizen, green card holder, or US tax resident, owning one triggers some of the harshest rules in the tax code. Gains get taxed as ordinary income at the top rate, an interest charge stacks on top, and you may owe a separate Form 8621 for every single fund. Below is what makes something a PFIC, why the tax hit is so painful, and what you can actually do about it.
What is a PFIC for US tax purposes?
A foreign corporation is a PFIC for any tax year in which it passes either of two tests in Internal Revenue Code section 1297. The IRS spells both out in its Instructions for Form 8621.
| PFIC test | What it checks | Threshold |
|---|---|---|
| Income test | Share of the company’s gross income that is passive (dividends, interest, royalties, rents, capital gains) | 75% or more |
| Asset test | Average share of the company’s assets that produce passive income or are held to produce it | 50% or more |
Pass one test and you have a PFIC for that year. A fund that exists to hold stocks and bonds sails past both, which is why almost every foreign mutual fund and foreign ETF lands in PFIC territory automatically.
A few details trip people up:
- “Foreign” means where the fund is organized, not what it holds. A US-domiciled ETF full of Japanese stocks is not a PFIC. An Irish-domiciled ETF full of US stocks is.
- The test runs every year. A company can be a PFIC one year and not the next.
- Look-through rule. If the corporation owns 25% or more (by value) of another company, it counts its share of that company’s income and assets.
- Start-up exception. Under section 1298(b)(2), a new company is not treated as a PFIC in its first year with gross income, as long as no predecessor was a PFIC and it is not a PFIC in either of the next two years.
What does PFIC stand for?
PFIC stands for passive foreign investment company. Congress created the category in the Tax Reform Act of 1986 to stop Americans from parking money in offshore funds, letting it compound with no US tax, and paying only a low capital gains rate decades later. The Wikipedia entry on PFICs has a decent history if you want the backstory.
What are common PFIC examples?
Most PFICs that regular people own fall into a handful of buckets:
- Foreign mutual funds, including the ones banks in India, the UK, Australia, or Singapore sell to everyday customers
- Foreign ETFs, such as UCITS ETFs listed in London, Amsterdam, or Frankfurt (often domiciled in Ireland or Luxembourg)
- Canadian ETFs and mutual funds, even the popular low-fee index ones
- Foreign unit trusts, investment trusts, and some insurance wrappers that hold funds inside them
- Foreign holding companies and startups that sit on lots of cash or investments relative to their operating business
What usually is not a PFIC: US mutual funds and US-domiciled ETFs, shares of large foreign operating companies (think a carmaker or bank whose income comes from real business), money sitting in a foreign bank account, and foreign rental property you own directly.
Why is a PFIC a problem for US investors?

A PFIC is a problem because the default tax treatment is built to be a penalty. Unless you make an election, you fall under the “excess distribution” regime of section 1291, and three things happen at once.
1. No capital gains rate
When you sell a PFIC at a gain, the whole gain is treated as an excess distribution. You lose the 0%, 15%, or 20% long-term capital gains rates you would get on a US fund.
2. The gain is taxed at the top rate for every past year
The gain (or any distribution that is more than 125% of the average you received over the prior three years) is spread evenly over each day you owned the shares. The slice that lands in the current year is ordinary income. Every slice that lands in an earlier PFIC year is taxed at the highest individual rate in effect for that year, no matter what bracket you were actually in. Per the IRS table, that top rate was 37% for 2018 through 2025 and 39.6% for 2013 through 2017.
3. An interest charge on top
The IRS then adds non-deductible interest on each prior-year slice, as if you had owed that tax back then and paid late. The longer you hold, the bigger this gets.
How much more tax does a PFIC really cost? A simple example
Numbers make this click. Say you put $30,000 into a European ETF, hold it for five years, and sell it for $50,000. That is a $20,000 gain. For simplicity, assume an even $4,000 of gain per year and that you sit in the 24% bracket.
| US-domiciled ETF | Foreign ETF (PFIC, default rules) | |
|---|---|---|
| How the gain is taxed | Long-term capital gain at 15% | Spread over 5 years, prior years at the top rate |
| Current year ($4,000) | Part of the 15% calculation | $4,000 × 24% = $960 |
| Prior 4 years ($16,000) | Part of the 15% calculation | $16,000 × 37% = $5,920 |
| Tax before interest | $3,000 | $6,880 |
| Interest charge | None | Yes, on each prior-year slice |
Same investment, same gain, and the PFIC version costs more than double before the interest charge is even added. Hold for 15 years instead of five and the gap gets ugly.
This is a simplified illustration. Real calculations allocate by days held, account for foreign tax credits, and use the IRS underpayment interest rates for each period.
How are PFICs taxed if you make an election?
You can escape the default regime with one of two elections, but each has strings attached.
| Default (Section 1291) | QEF election | Mark-to-market election | |
|---|---|---|---|
| When you pay tax | On distributions and sale | Every year, on your share of fund earnings | Every year, on the change in value |
| Character of gain | Ordinary, top rate + interest | Ordinary earnings plus long-term capital gain share | Ordinary income |
| Interest charge | Yes | No | No |
| What you need | Nothing | A PFIC Annual Information Statement from the fund | Shares that are “regularly traded” on a qualifying exchange |
QEF election
A qualified electing fund (QEF) election under section 1295 makes you include your share of the fund’s ordinary earnings and net capital gain each year, even if you receive nothing in cash. The upside: you keep capital gains treatment on that portion and avoid the interest charge. The catch is that the fund must give you a PFIC Annual Information Statement. Some fund families that court US investors provide them (BlackRock Canada, for instance, publishes PFIC statements for its Canadian funds), but many foreign funds simply don’t.
Mark-to-market election
If the PFIC is marketable stock, meaning it trades regularly on a qualifying exchange, you can elect under section 1296 to treat it as if you sold it on the last day of each year. Gains are ordinary income. Losses are only deductible up to the gains you already reported in earlier years. It is simpler than QEF and works for most listed foreign ETFs, though you pay tax on paper gains you haven’t cashed out.
Timing matters with both. An election made in your first year of owning the fund is clean. Make it later and the earlier years can still drag the default rules along unless you do a “purging” election, which usually means recognizing gain up front.
Do you have to file Form 8621 for a PFIC?
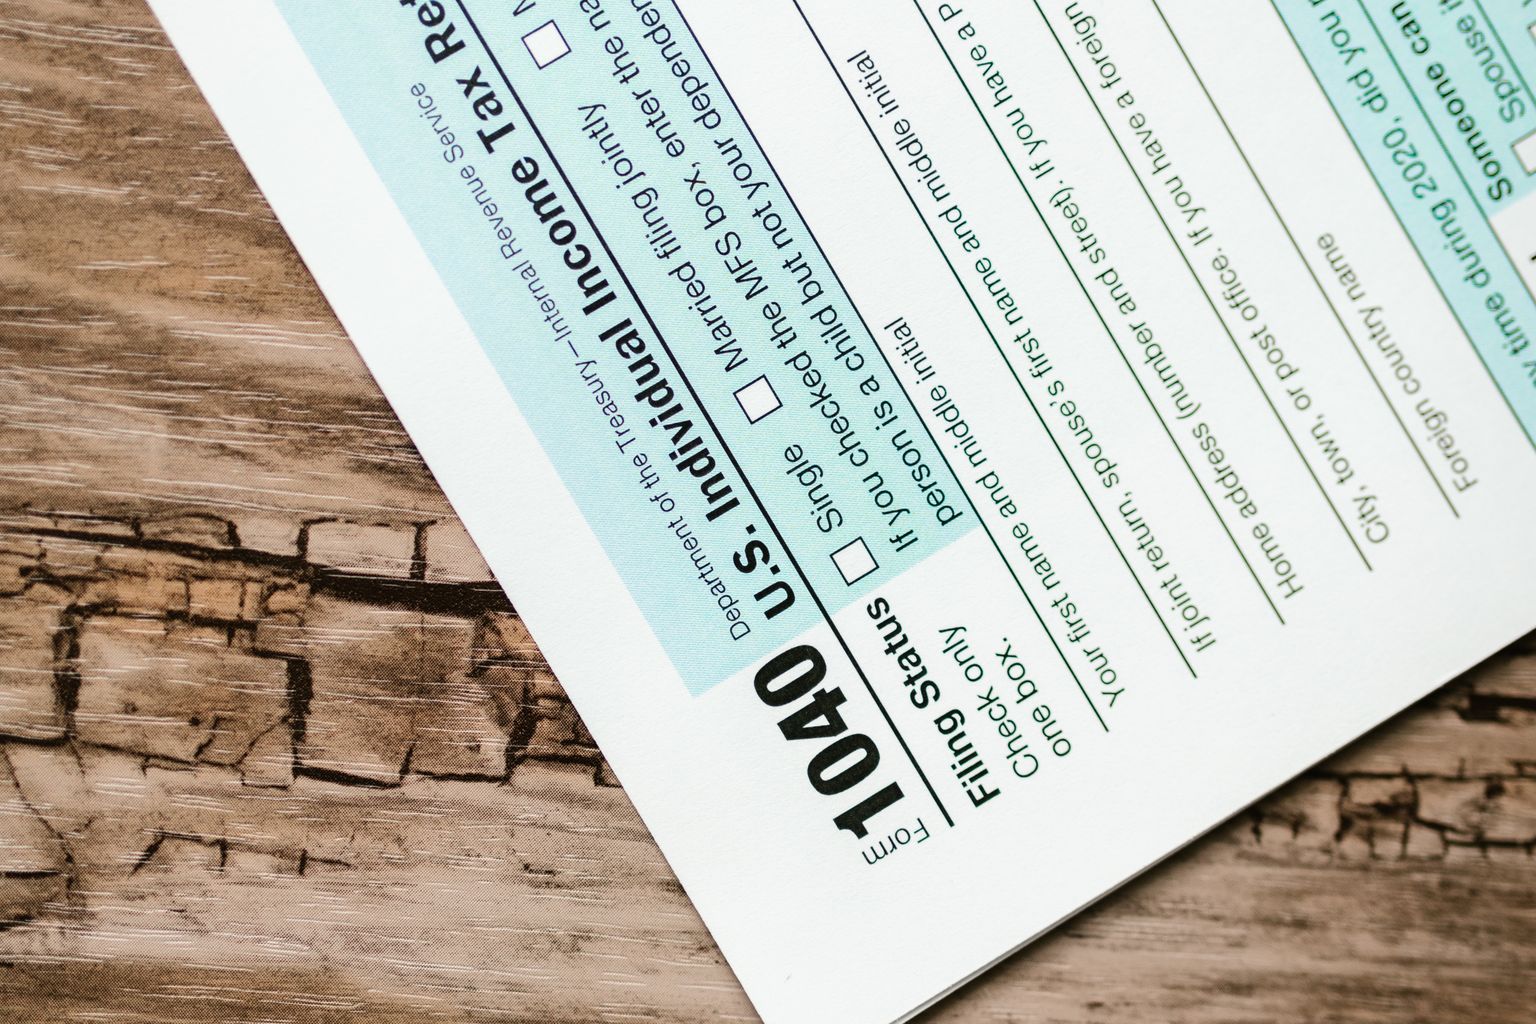
Often, yes. Form 8621 is the IRS information return for PFIC shareholders, and you file a separate form for each PFIC, attached to your tax return by its due date (including extensions). According to the IRS instructions, you generally have to file if you:
- Receive certain distributions from a PFIC
- Sell or dispose of PFIC shares at a gain
- Are reporting under a QEF or mark-to-market election
- Are making an election on the form
- Are otherwise required to file an annual report under section 1298(f)
The $25,000 exception
There is some relief for small holdings. You don’t have to complete the annual summary (Part I) for a section 1291 fund if the total value of all your PFIC stock is $25,000 or less ($50,000 on a joint return) on the last day of your tax year, and you had no excess distribution and no gain from selling that fund. Indirect holdings through another PFIC have a lower $5,000 threshold. The exception disappears the moment you sell at a gain or receive an excess distribution.
What happens if you don’t file Form 8621?
There is no fixed dollar penalty for a missing Form 8621, but the bigger issue is the statute of limitations. Under section 6501(c)(8), the IRS’s time to assess tax stays open until three years after you provide the missing information. If the failure wasn’t due to reasonable cause, that can keep your entire return open, not just the PFIC part.
PFIC reporting also sits alongside, not in place of, your other foreign account filings. A PFIC held in a foreign brokerage can count toward your FBAR and Form 8938 thresholds, which our FBAR vs FATCA guide explains in plain English.
How can you tell if a fund is a PFIC?
Start with where the fund is legally organized. Check the fund’s fact sheet or prospectus for its domicile, or look at the first two letters of its ISIN: “US” points to a US fund, while “IE” (Ireland), “LU” (Luxembourg), “CA” (Canada), or “IN” (India) signals a foreign one. If it is a foreign-organized fund that holds stocks, bonds, or cash, assume it is a PFIC until a professional tells you otherwise.
For individual foreign company shares, it is murkier. Most large operating businesses are not PFICs, but some companies flag their status in annual reports, especially ones with big cash piles or investment portfolios. When in doubt, search the company’s investor relations page for “PFIC.”
How do you avoid PFIC problems?
The cleanest fix is not owning PFICs in the first place. Practical moves that work for most people:
- Buy US-domiciled funds for international exposure. A US-listed total international ETF gets you the same markets without PFIC rules.
- Hold PFICs inside a US retirement account. Foreign funds held through a US IRA or 401(k) generally sit outside the PFIC tax regime because the account itself is tax-exempt. Confirm with your preparer, since few US brokers offer foreign funds anyway.
- Own individual foreign operating company stocks instead of foreign funds, if you want local market exposure.
- Make the election in year one if you do hold a PFIC: QEF when the fund provides the statement, mark-to-market when it is listed.
- Clean up before you move. If you are leaving a country, or a holder of an H-1B or green card whose home-country investments now fall under US tax, review your portfolio early. Our guide on what to do after an H1B layoff touches on the money side of visa transitions too.
There is a real trap for Americans living in Europe here. EU retail investors often can’t buy US-domiciled ETFs because those funds don’t publish the key information document required under EU PRIIPs rules. So US expats in Europe are frequently stuck choosing between PFIC-heavy local ETFs, individual stocks, or keeping a US brokerage account, which not every US broker allows for non-residents. If retirement saving is the goal, maxing out US accounts where you still qualify can sidestep the whole issue, as our Roth IRA vs 401(k) comparison covers.
Conclusion
So, what is a PFIC? It is any foreign corporation, most often a foreign mutual fund or ETF, that earns mostly passive income or holds mostly passive assets. For US taxpayers, that label turns an ordinary investment into a tax headache: top-rate tax on gains, an interest charge for every year you held, and a separate Form 8621 for each fund. The best defense is choosing US-domiciled funds from the start. If you already own PFICs, look at a QEF or mark-to-market election and get a cross-border tax preparer involved before you sell. For more plain-English money guides, browse the rest of Da Finance Blog.
Frequently Asked Questions
Q1: What is a PFIC in simple terms?
A: A PFIC is a foreign company or fund that mainly earns investment income or holds investment assets. If 75% of its income is passive or 50% of its assets are passive, the IRS treats it as a PFIC.
Q2: Is a foreign ETF a PFIC?
A: Almost always, yes. A foreign-domiciled ETF holds stocks or bonds, so it passes the income and asset tests easily. US-domiciled ETFs are not PFICs, even if they invest abroad.
Q3: Are individual foreign stocks PFICs?
A: Usually not. Shares of a foreign operating company, like a manufacturer or bank, generally fail both tests. Companies holding large amounts of cash or investments relative to their business can be exceptions.
Q4: What is the PFIC income test and asset test?
A: The income test asks whether 75% or more of gross income is passive. The asset test asks whether 50% or more of average assets produce passive income. Passing either makes the company a PFIC for that year.
Q5: How is PFIC income taxed?
A: By default, gains and excess distributions are spread over your holding period, taxed at the top ordinary rate for past years, and charged interest. A QEF or mark-to-market election replaces this with annual taxation.
Q6: Do I need to file Form 8621 if I hold a small amount?
A: Possibly not. If all your PFIC stock is worth $25,000 or less ($50,000 joint) at year-end and you had no excess distribution or sale gain, you can skip Part I for that fund.
Q7: What happens if I don't file Form 8621?
A: There is no fixed penalty, but the statute of limitations on your return stays open until three years after you file the missing information, giving the IRS more time to audit.
Q8: Does a PFIC need to be reported on the FBAR?
A: The account holding it may need to be. FBAR covers foreign financial accounts over $10,000 in aggregate, and Form 8938 has its own thresholds. Both are separate from Form 8621.
2 comments
[…] your Form 8938 threshold. Foreign mutual funds are the usual culprit, so read our explainer on what a PFIC is if you hold funds […]
[…] 8621 on top of the FBAR and Form 8938. PFIC tax rules are harsh and complicated, so see our guide What is a PFIC? before you file. Some foreign trusts, and certain foreign pension or savings plans that the IRS […]